COMMERCIAL INSURANCE · FISCHER RISK MANAGEMENT

Bigger contracts. New products. Is your insurance keeping up?

A new retailer. More inventory. A bigger customer contract. Work with Cory Fischer to review commercial insurance around the business you run today and the commitments you are making next.

Request an Insurance Review
Consumer products, a cargo ship, and business professionals reviewing work together.

WHO WE WORK WITH

Your industry changes the questions we ask.

Ingredients, components, code, and customer contracts create different exposures. Start with the guide that sounds like your business.

Consumer-products inventory in a distribution facility.

01 / INDUSTRIES

Consumer brands & e-commerce

Connect your insurance review to how you source products, sell online, and expand into retail and wholesale.

Explore consumer brands & e-commerce →
Apparel professionals examining a garment in a design studio.

02 / INDUSTRIES

Apparel & lifestyle

Consider product liability, sourcing, inventory, and distribution for clothing, footwear, and accessories businesses.

Explore the apparel & lifestyle industry →
Beauty product professionals reviewing samples and quality documentation.

03 / INDUSTRIES

Beauty & personal care

Review the needs of cosmetics, skincare, and personal care product brands as products and sales channels evolve.

Explore the beauty & personal care industry →
Ultrasound equipment and probe on a medical device development bench.

04 / INDUSTRIES

Medical device businesses

Commercial insurance for device developers, manufacturers, and distributors.

Explore the medical device industry →
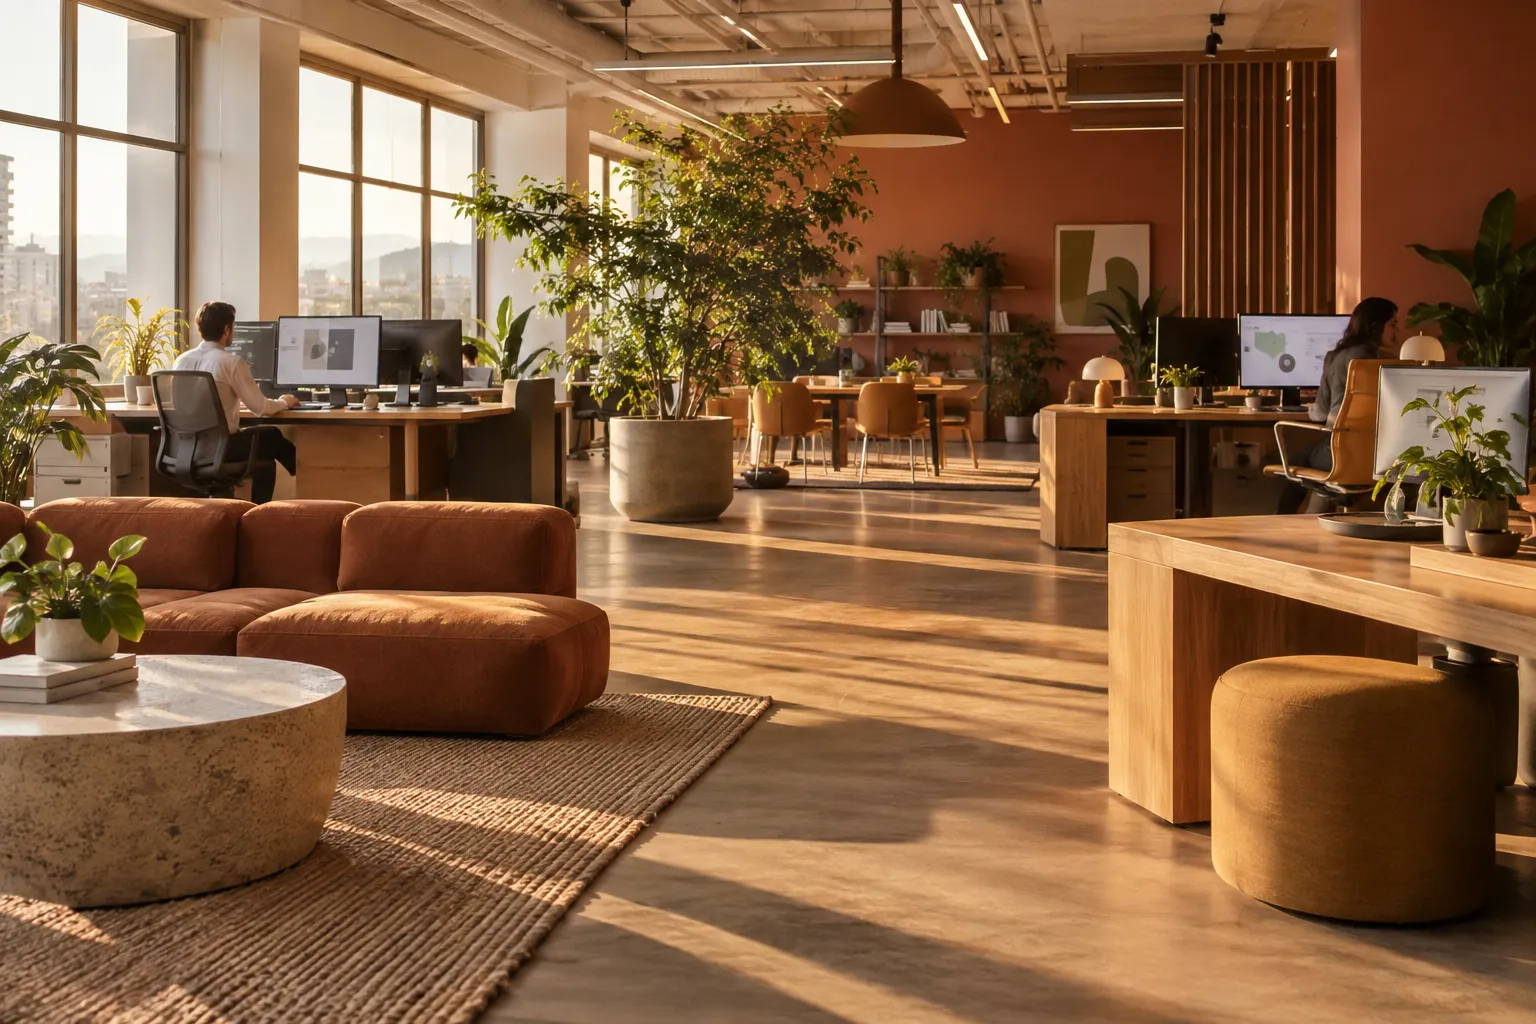
A spacious software-company workspace with warm wood desks and distant staff.

05 / INDUSTRIES

Technology & SaaS

Bring technology services, customer contracts, cyber exposures, and leadership risks into one conversation.

Explore the technology & SaaS industry →
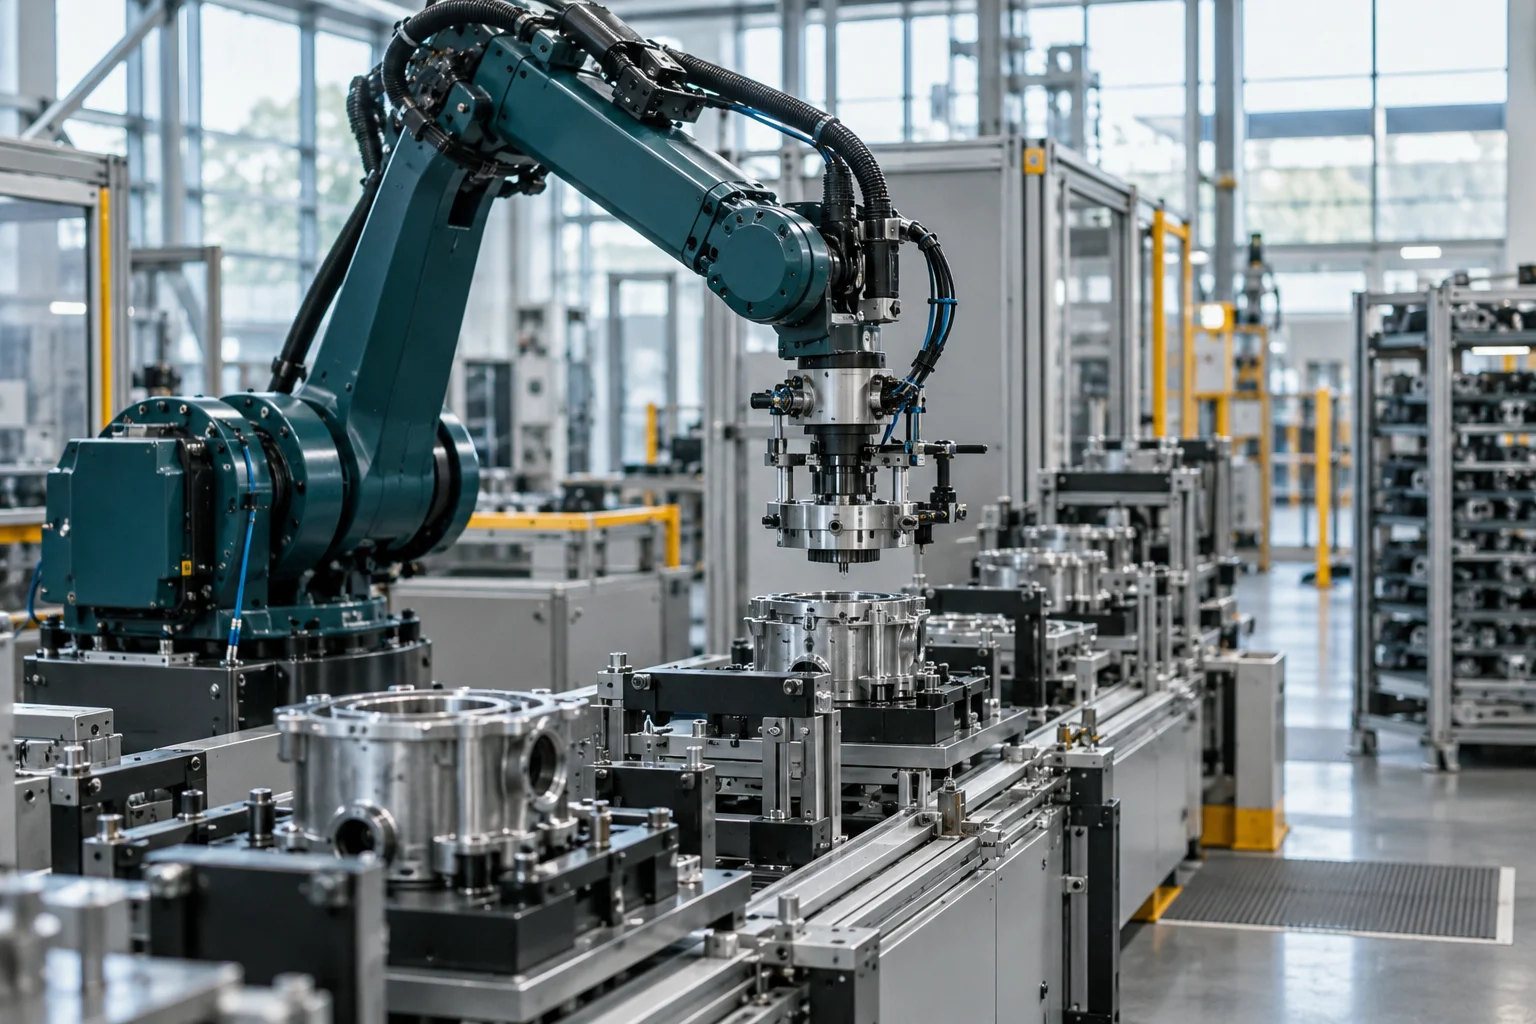
Industrial robotic arm assembling metal components on a clean manufacturing line.

06 / INDUSTRIES

Manufacturers, importers & distributors

Review the insurance needs of making, sourcing, storing, and distributing goods.

Explore Manufacturers, importers & distributors →
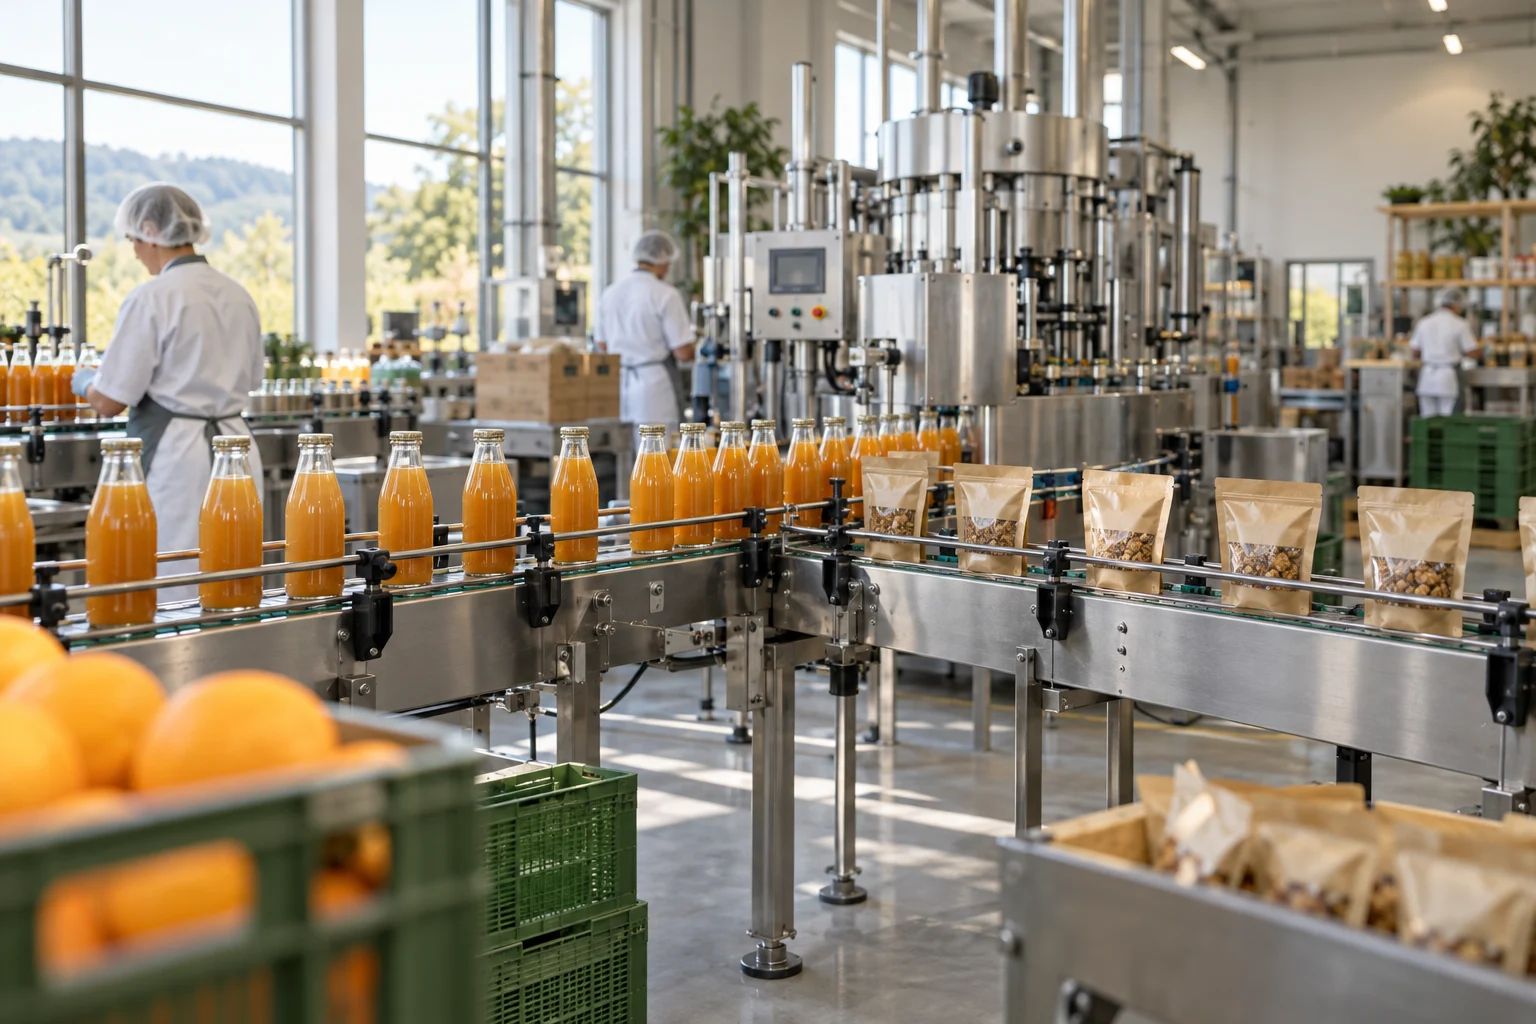
Bottled juice and packaged snacks moving through a sunlit food and beverage production facility.

07 / INDUSTRIES

Food & beverage brands

Connect food production, recall, inventory, and distribution to your insurance review.

Explore Food & beverage brands →
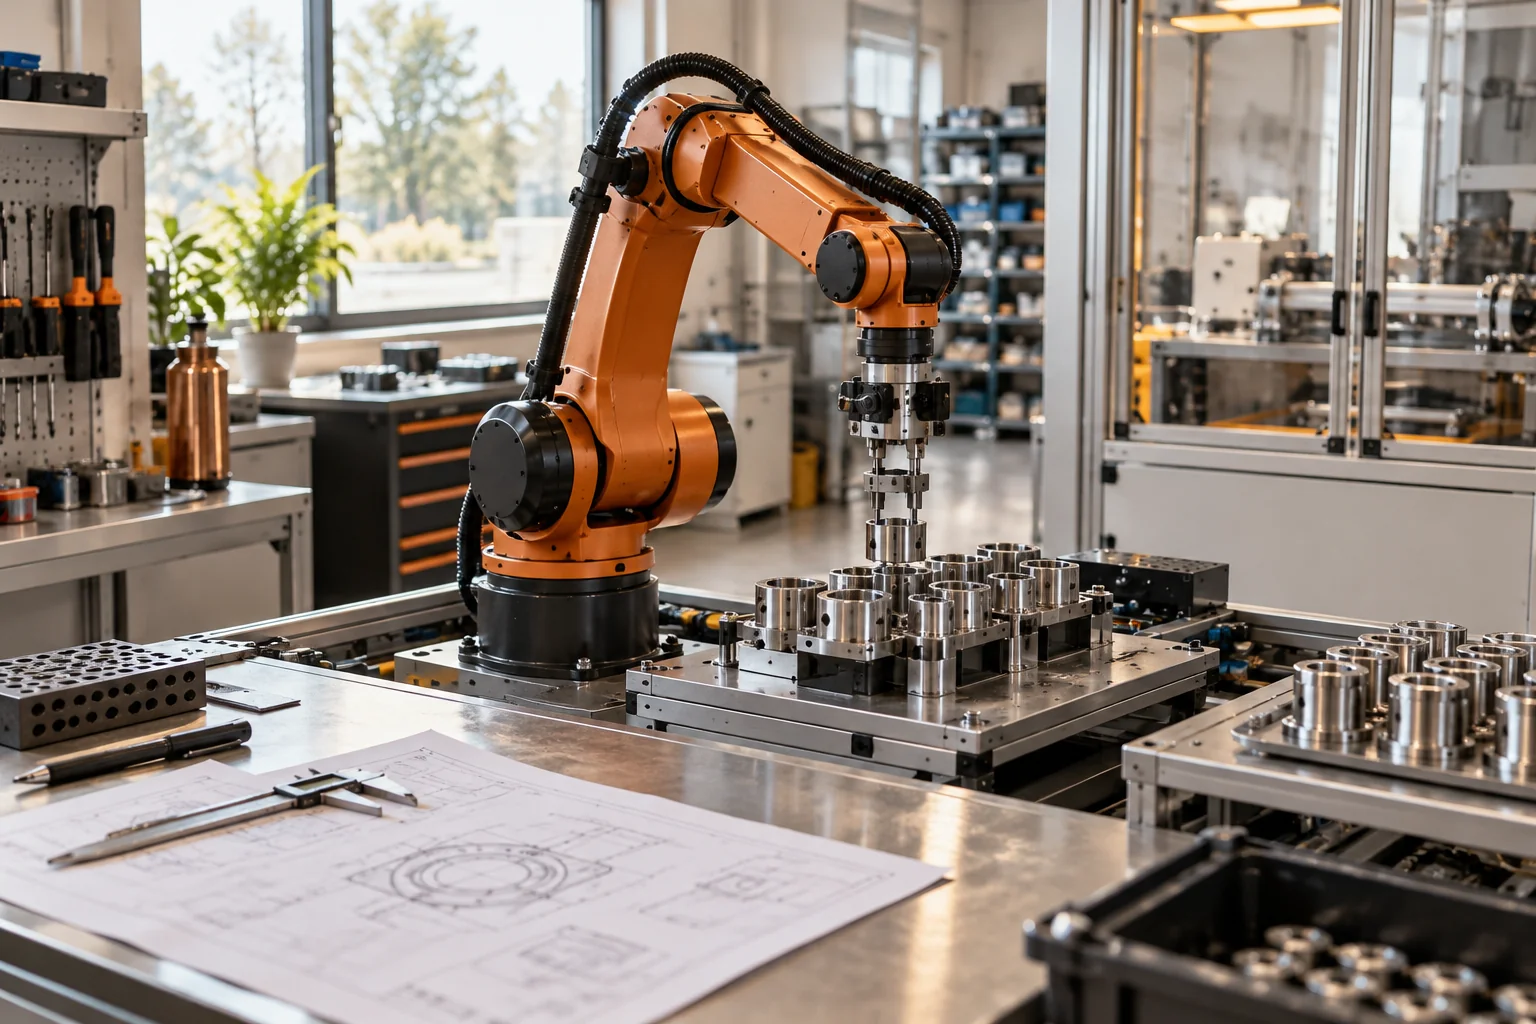
An orange industrial robotic arm assembling precision components in a bright manufacturing cell.

08 / INDUSTRIES

Robotics & Automation

Hardware, software, installation, and customer promises meet in one system. Review the business behind your robotics and automation solutions.

Explore Robotics & Automation →
Two engineers reviewing model evaluation charts at separate workstations in a daylight AI development office.

09 / INDUSTRIES

AI & AI-Enabled Businesses

What does your AI do, and what do customers rely on it to get right? Review services, data responsibilities, and customer commitments together.

Explore AI & AI-Enabled Businesses →
Notebook, calculator, and folder arranged for a business review.

YOUR NEXT STEP

Start with your business.

Tell us what your company does, what is changing, and when you need coverage.

Request an Insurance Review →

COVERAGE TO EXPLORE

One business. Risks that cross policy lines.

A product issue can raise liability, recall, and income questions. A customer contract can bring E&O, cyber, and higher limits into the same conversation. Explore how the pieces relate.
A bicycle helmet undergoing a strap check at a product design workbench.

Product liability

Review liability exposures connected with the products your business manufactures, distributes, or sells.

Explore Product liability →
Precision metal component being measured with a caliper at a manufacturing quality-control workbench.

Product E&O / Manufacturers E&O

Review financial-loss exposures when your product fails to perform as expected.

Explore Product E&O / Manufacturers E&O →
Product bottles passing through an automated quality inspection line.

Product recall

Evaluate recall-related exposures alongside your broader product insurance program.

Explore Product recall →
Container ship, cranes, and freight containers at an ocean cargo terminal.

Inventory, cargo & stock throughput

Review how goods are insured through transit, storage, and distribution.

Explore Inventory, cargo & stock throughput →
Detailed view of a processor and electronic circuit board.

Technology errors & omissions

Discuss risks connected with technology products, professional services, and customer agreements.

Explore Technology errors & omissions →
Server racks in a blue-lit data center aisle.

Cyber insurance

Review insurance needs related to data, systems, and cyber incidents.

Explore Cyber insurance →
Business leaders reviewing documents around a boardroom table.

Management liability

Consider leadership and employment-related exposures as your organization develops.

Explore Management liability →
Sunlit business reception lobby with glass entrance doors and a visitor counter.

General liability

Review premises, operations, and customer contract requirements within your insurance program.

Explore General liability →
Orange safety helmet, work gloves, and protective eyewear on a workshop bench.

Workers’ compensation

Review employee duties, payroll, and work locations as your business grows.

Explore Workers’ compensation →
Consumer device prototype, concept sketches, and calipers on a design studio table.

Intellectual property

Explore specialist infringement defense and enforcement insurance for products, brands, and technology.

Explore Intellectual property →
Commercial building and loading doors in early morning light.

Commercial Property & Business Interruption

Review buildings, equipment, inventory, and business income together, including recovery time and supply-chain dependencies.

Explore Commercial Property & Business Interruption →
Glass and steel canopy covering a business campus walkway after rain.

Umbrella & Excess Liability

Review additional liability limits, underlying policies, customer requirements, and the structure of your excess insurance program.

Explore Umbrella & Excess Liability →
Payment approval documents, calculator, key, and authentication token on a finance desk.

Crime & Fidelity

Explore employee theft, payment fraud, funds transfer exposures, and the relationship between crime and cyber insurance.

Explore Crime & Fidelity →
HR manager and employee talking across a table in a bright office.

Employment Practices Liability (EPLI)

Review employment-related claims, defense costs, workforce changes, and EPLI terms alongside your management liability program.

Explore Employment Practices Liability (EPLI) →
Executive boardroom with an oak table and city skyline windows.

Directors & Officers (D&O)

Review leadership liability, investor expectations, insured entities, and D&O terms for a growing private company.

Explore Directors & Officers (D&O) →
Consultant planning desk with drawings, notebook, and measuring tools.

Professional Liability / E&O

Review liability arising from advice and professional services, including client contracts, insured activities, and claims-made terms.

Explore Professional Liability / E&O →
Selected insurance markets

CFC
Counterpart
Travelers
The Hartford
Chubb
The Hanover
Coalition
Markel
Great American
Berkshire Hathaway GUARD
Liberty Mutual
AXIS
Scottsdale / Nationwide E&SScottsdale / Nationwide E&S
Berkley
Ascot Specialty
At-Bay
CNA

Has your business outgrown its insurance program?

Larger contracts. More inventory. New markets. Acquisitions. The insurance program that fit your business a few years ago may need a closer look today. Review how coverage, limits, and contractual requirements align with the business you operate now and where it is headed.

Request an Insurance ReviewAn advisor and business owner walking through a manufacturing facility.

01 Map what has changed.

Review revenue growth, new products, distribution, locations, and acquisitions with the leaders responsible for finance and operations.

02 Examine the whole program.

Look at limits, exclusions, deductibles, and overlapping policies alongside customer contracts, supply chains, and the risks your business retains.

03 Plan for what comes next.

Prioritize coverage decisions, prepare for renewal, and pursue insurance options that reflect your current operations and planned growth.

FISCHER RISK MANAGEMENT / RESOURCES

A contract to sign. Inventory to move. A renewal to prepare.

Use these practical guides to ask better questions before the next business decision.

A retailer sent insurance requirements. What should you check?Product liability vs. product E&O: what is the difference?Your renewal is coming. Start with what changed.Explore all business insurance resources →

When the business changes, they call Cory.

Hear from the finance and operations leaders who count on Cory for clear answers, thoughtful advice, and follow-through.

An answer, not another follow-up.

“Cory is the most responsive broker I have worked with. He answers the same day, usually within the hour, with an actual answer. He took the time to understand how our business really works before approaching an underwriter, and it showed in the terms he brought back. He has also told me when the right move was to wait. I trust his judgment.”

Charlie Mertz

Chief Financial Officer
Apollo Information Systems Corp.

A partner between renewals.

“I’ve worked with plenty of insurance brokers, both for my own company and for the brands I support as a fractional CFO. Cory Fischer is one of the best. He regularly checks in, understands how the business is evolving, and puts his clients’ interests first. When I call, he answers. When I email, he responds quickly. He’s much more than a broker. He’s a trusted advisor.”

Matt Sommers

President
Solid Ratio

Read Matt’s full testimonial

I've worked with plenty of insurance brokers over the years, both for my own company and through the brands I support as a fractional CFO, and Cory Fischer is truly one of the best.

What sets Cory apart is his proactive approach and genuine interest in the businesses he supports. He's not someone you hear from once a year at renewal. He regularly checks in, takes the time to understand how the business is evolving, and ensures the coverage keeps pace. He's incredibly knowledgeable, always willing to discuss any situation, and consistently puts his clients' interests first.

When renewal comes around, he hustles to find the best coverage at the best possible value. And his responsiveness is second to none. When I call, he answers, and when I email, he's quick to respond.

Cory is much more than an insurance broker. He's a trusted advisor, and I couldn't recommend him more highly.

Advice with our interests at heart.

“Cory has been a great partner for our business. He’s knowledgeable, responsive, and takes the time to understand our needs and make sure we have the right coverage in place. Most importantly, he looks out for our best interests. I would highly recommend him to any business looking for a trusted insurance advisor.”

Ross Gelber

Chief Operating Officer
Event Cadence

Support from day one.

“Cory has been extremely supportive as our startup has grown over the years. He’s responsive, knowledgeable, and has given us good advice throughout that growth. I feel lucky we found him from day one.”

Luke Spieldenner

Events Director & Business Manager
Ashley Systems

COMMON QUESTIONS

Good questions before the next renewal.

Can I request a quote if I already have insurance?

Yes. Include your renewal date and tell us why you’re reviewing coverage. Existing policies and relevant contracts can help inform the next conversation.

What information should I provide to get started?

Start with your business website, industry, annual revenue range, and timing. Additional information will depend on your operations and the coverage you are seeking.

Is this for medical device businesses or personal medical coverage?

This site focuses on commercial insurance for medical device businesses, including developers, manufacturers, and distributors. It is not a patient health insurance or device reimbursement service.

Can we discuss several types of insurance together?

Yes. Tell us which policies you have and what you want to review. The conversation can address multiple insurance needs across your business.

YOUR INSURANCE CONTACT

Work directly with Cory Fischer.

Cory Fischer is a licensed Property & Casualty producer with experience in commercial insurance. At Fischer Risk Management, the conversation starts with how your business operates: the products you sell, the partners you rely on, and the plans you have for growth.

For product businesses, that means looking at sourcing, manufacturing, distribution, and customer requirements together. For technology and SaaS companies, it means considering services, contracts, and data alongside the broader insurance program.

Work directly with Cory to discuss product liability and related insurance needs for consumer brands, apparel, beauty and personal care, medical devices, and technology businesses.

Cory Fischer | Colorado insurance producer license 779802

Talk with Cory
Cory Fischer, Fischer Risk Management
Cory Fischer
Fischer Risk Management

LET’S START THE CONVERSATION

Tell us what changed. Let’s review the insurance.

A renewal coming up? A contract to meet? A new product on the way? Share your business website and timing. Cory will follow up to discuss what changed, what you want to review, and the information needed for the next step.

“He took the time to understand how our business really works before putting anything in front of an underwriter, and it showed in the terms he brought back.” | Charlie Mertz, Chief Financial Officer, Apollo Information Systems Corp.

Submitting an inquiry does not bind coverage. Coverage availability and terms depend on underwriting and the policy issued.

Thank you. Your quote request has been received. Submitting a request does not bind coverage.
Your request could not be sent. Please try again.

Please provide business contact details only. Do not include personal medical information or sensitive policy documents.