
FISCHER RISK MANAGEMENT / INDUSTRIES

Insurance for consumer brands. Bigger orders change the risk.

A new retailer. A larger inventory commitment. A product category you have never sold before. Bring those changes into your insurance review before the next order ships.
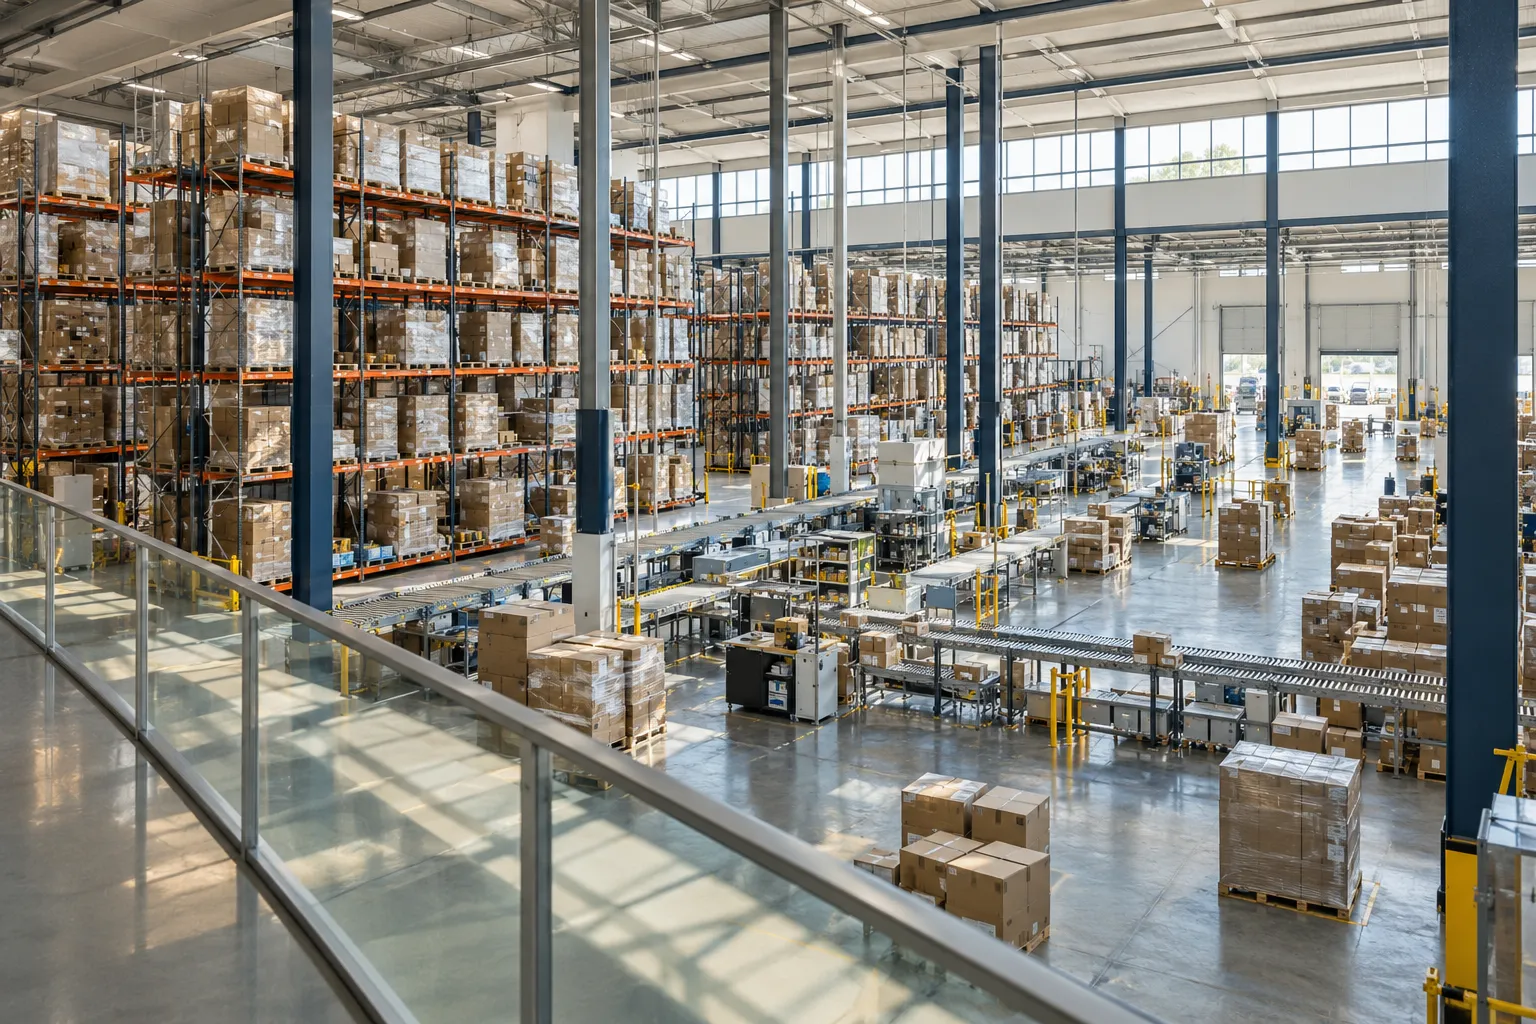
Orderly consumer-products distribution facility.Request an Insurance Review

Explore coverage guides

Product Liability

Product Recall

Inventory, Cargo & Stock Throughput

Technology Errors & Omissions

Cyber Insurance

Management Liability

Your brand sells the product. Map who carries the risk.

Selling through your own website, marketplaces, and retail partners brings different insurance questions into the same business. Fischer Risk Management starts with your products and operations, then considers the insurance program around them.

Bring the details behind your next move.

Products and sourcing

What do you sell, who manufactures it, and which quality-control responsibilities sit with your company? Include private-label products and imported goods in the discussion.

Inventory and fulfillment

Where do you own goods, how do they move, and who stores them? Share warehouse and fulfillment arrangements, seasonal stock peaks, and international shipments.

Sales channels and contracts

Tell us about your direct-to-consumer website, Amazon or other marketplaces, wholesale customers, and retail relationships. Bring their actual insurance requirements for review.

Connect the policies with the way you operate.

Product liability, product recall, inventory and cargo, cyber, and management liability may all belong in the discussion. The relevant combination depends on your business; no single coverage label establishes that every exposure is insured.
Container ship, cranes, and freight containers at an ocean cargo terminal.

Connect the product, inventory, and sales channel

A brand can own inventory in a supplier's facility, on the water, and in a third-party warehouse at the same time. A launch can also introduce a new product category or retailer agreement. Map those changes together so the insurance review addresses where the goods are, what your company does, and which contracts need attention.

A bicycle helmet undergoing a strap check at a product design workbench.

What should a growing consumer brand prepare?

Prepare a current product list, revenue by product or channel where available, manufacturing locations, typical and peak stock values, and the countries where you sell. Include the legal entities involved, relevant customer and supplier agreements, current policies, and loss history. For an initial inquiry, share your business website and timing; Cory can explain how to provide detailed documents appropriately.

Does a fulfillment provider insure our inventory?

Do not assume the provider's insurance covers your goods on the terms your business needs. Bring the storage agreement and explain ownership, valuation, and locations. Review the provider's obligations alongside your own cargo, stock throughput, or property arrangements.

When is a useful time to start?

Start when the renewal date, new sales agreement, shipment, or product launch becomes clear. Share the deadline and the changes you expect. Quotes and placement timing depend on the information needed and the markets available; submitting a request does not create coverage.

Explore coverage for your business

Review the broader business program

Include premises and operations, employee exposures, and specialist intellectual property questions in the conversation when relevant to your business.

A larger order or a new retailer on the horizon?

Tell Cory what you sell, where you sell it, and what the next agreement requires. Cory will follow up to discuss the business and the information needed for the next step.

Request an insurance review with Cory or call 845-721-0744.

Preparing for the conversation? Download the business insurance review checklist (PDF). No signup required.

Practical reading before your next decision

Explore all business insurance resources

Submitting an inquiry does not bind, amend, or cancel coverage. Coverage availability and terms depend on underwriting and the policy issued.

Does marketplace insurance address the whole business?

A marketplace requirement is a starting point for a specific relationship. Review it alongside your other operations, inventory, and contracts rather than assuming it describes everything the company needs.

Coverage availability, limits, exclusions, and terms depend on underwriting and the policy issued. A quote request does not bind coverage.

‍