
FISCHER RISK MANAGEMENT / INDUSTRIES
Seasonal inventory, overseas sourcing, and retailer agreements all shape the insurance conversation. Review the next collection alongside the operations and commitments behind it.
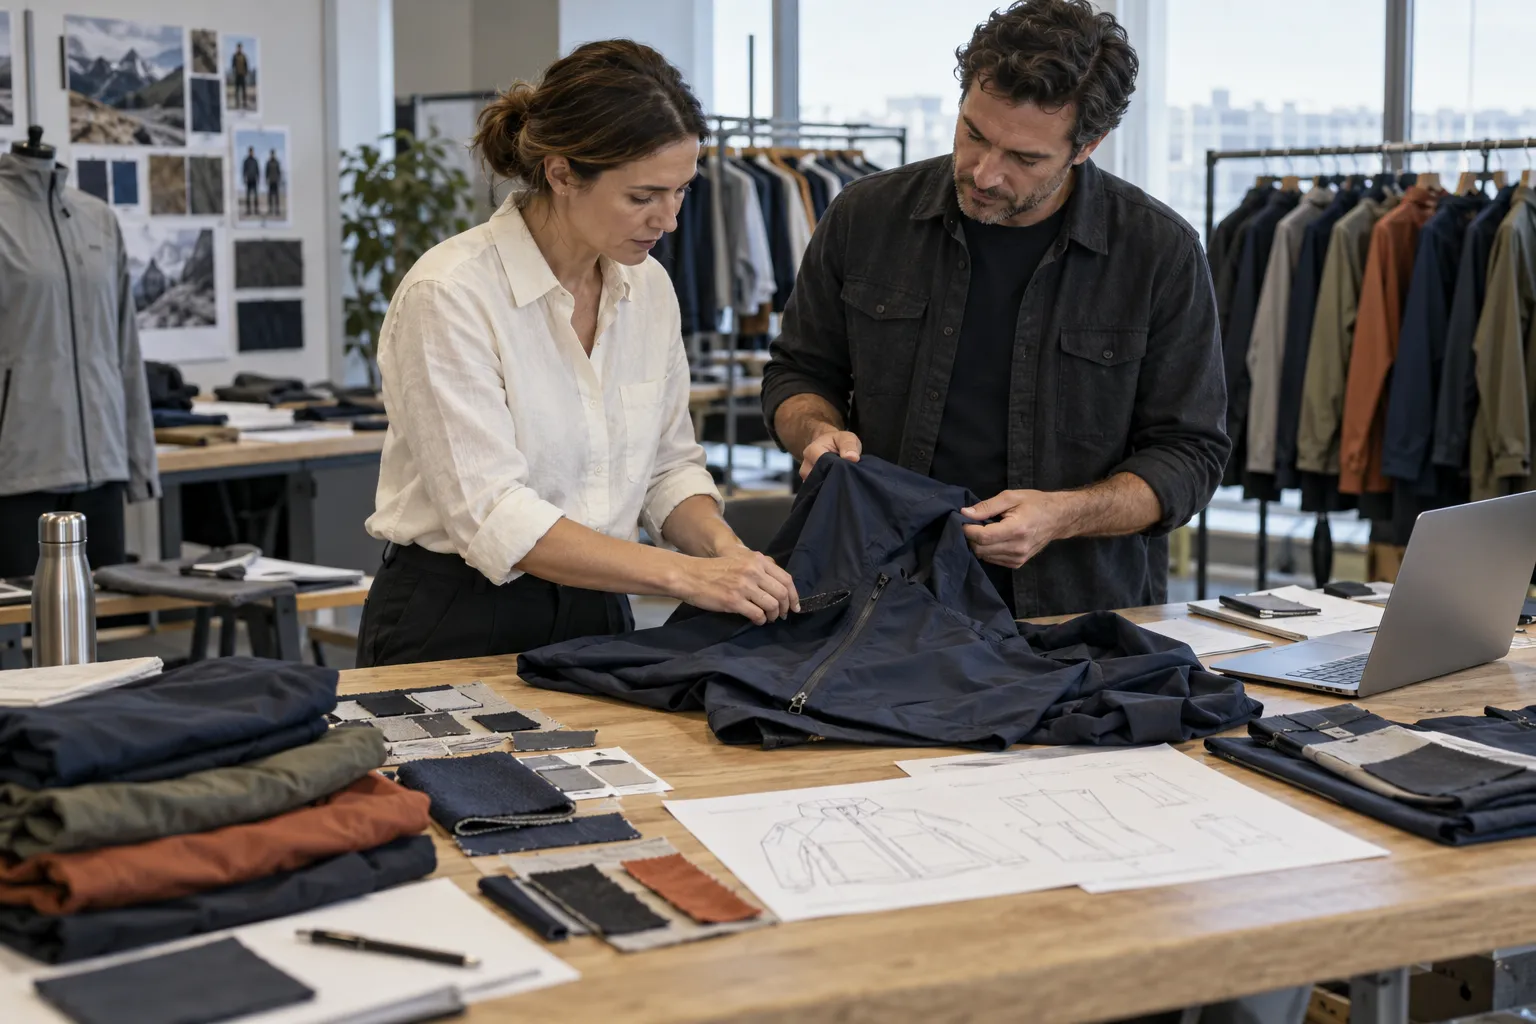
Request an Insurance ReviewAn apparel brand can have exposure across design, contract manufacturing, shipping, storage, and sales. Start with how your business actually operates, whether you sell direct to consumers, through retailers, or both.
Describe clothing, footwear, accessories, and any specialist uses or customer groups. Include new categories you plan to launch, not just last year’s product list.
Identify overseas suppliers, manufacturing partners, warehouses, and fulfillment providers. Bring typical and peak inventory values and explain when ownership of goods changes.
Share contracts, distribution changes, and upcoming launches. A business entering national retail may have different review priorities from one selling only through its own website.
The conversation can include product liability, inventory and cargo, recall exposures, and other commercial policies. Review values, limits, and policy wording together instead of comparing premium alone.
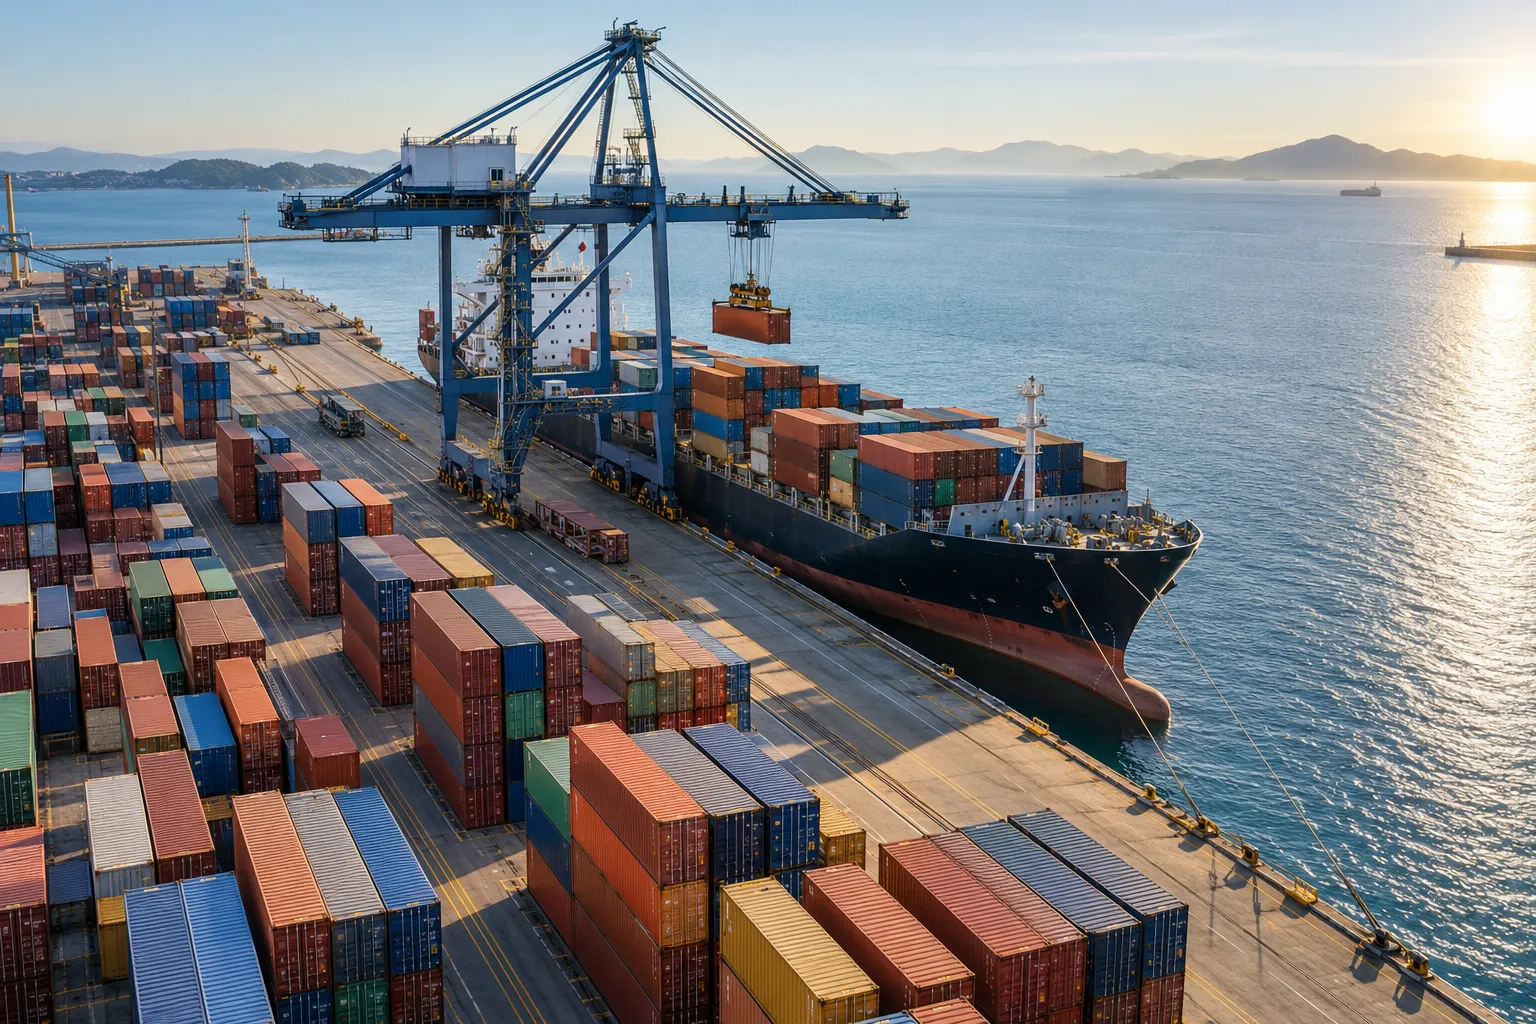
An apparel company may have samples, finished goods, and returned products across several locations. Explain seasonal peaks, overseas production, transit routes, and how you value the stock. Include footwear, children's products, accessories, or specialist garments when relevant, so the review reflects the actual product mix.
Bring the retailer's agreement and insurance requirements before the planned launch. Review requested limits, additional-insured terms, and the entities named in the agreement against the proposed policies. A certificate summarizes information; the underlying coverage and endorsements determine the protection provided.
Do not assume it does. A supplier's insurance, the manufacturing contract, and your brand's own policy each need attention. Explain private labeling, importing, design responsibilities, quality controls, and who handles customer complaints so the review can identify relevant underwriting questions.

Begin with your website, current coverage, renewal date, revenue, and upcoming launches. For the detailed review, organize supplier locations, stock values, sales territories, loss history, and customer contracts. Tell Cory whether you also operate stores, employ staff, or provide services so those activities can be considered with the broader program.
Include premises and operations, employee exposures, and specialist intellectual property questions in the conversation when relevant to your business.
Share your sourcing arrangements, sales channels, and the timing of your next launch or renewal. Cory will follow up to discuss the business and the information needed for the next step.
Request an insurance review with Cory or call 845-721-0744.
Preparing for the conversation? Download the business insurance review checklist (PDF). No signup required.
Explore all business insurance resources
Submitting an inquiry does not bind, amend, or cancel coverage. Coverage availability and terms depend on underwriting and the policy issued.
Yes. Bring the proposed retailer requirements, launch timing, product information, and your existing policies. That helps identify the information needed before approaching insurers.
Coverage availability, limits, exclusions, and terms depend on underwriting and the policy issued. A quote request does not bind coverage.