
FISCHER RISK MANAGEMENT / INDUSTRIES

Beauty brand insurance. A new formula changes the conversation.

New ingredients, contract manufacturers, and bigger distribution deals deserve a fresh look. Connect the products on the shelf with the agreements and inventory behind your brand.
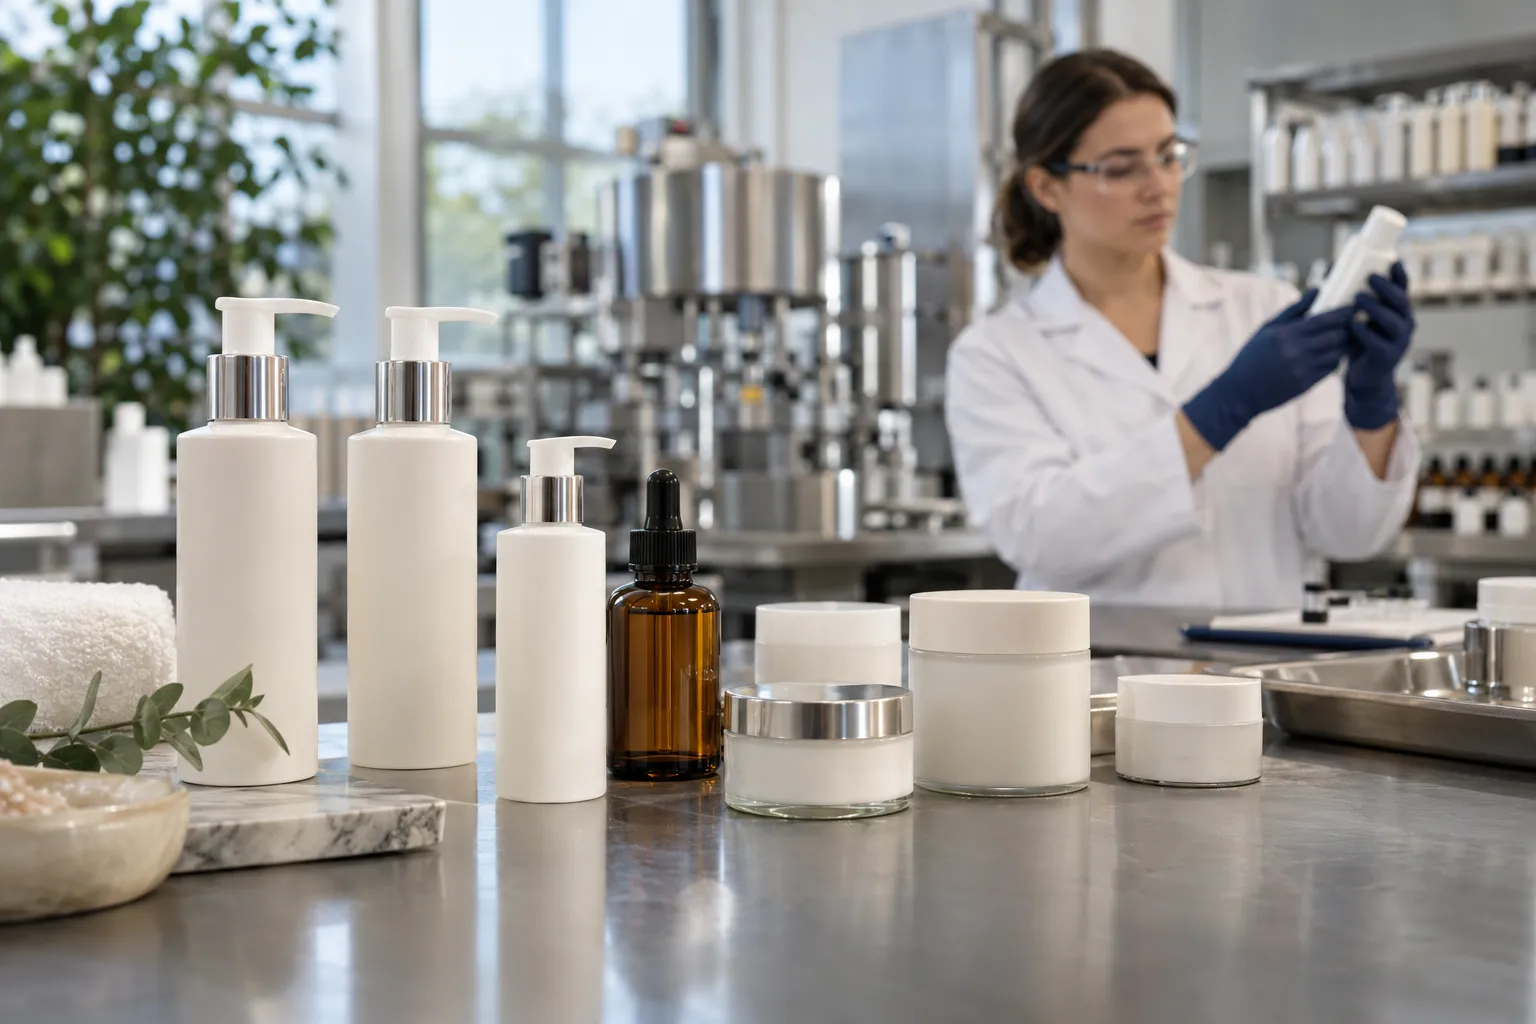
Beauty product professionals reviewing samples and quality documentation.Request an Insurance Review

Explore coverage guides

Product Liability

Product Recall

Inventory, Cargo & Stock Throughput

Technology Errors & Omissions

Cyber Insurance

Management Liability

New ingredients. New claims. New questions to ask.

This page is for businesses that develop, manufacture, import, distribute, or sell beauty and personal care products. The review starts with what you sell and how it reaches the customer.

Bring the details behind your next move.

Products and intended use

Provide the product range, ingredients information where relevant, intended uses, and the claims made in labels and marketing. Identify planned launches or material changes.

Manufacturing and quality controls

Explain whether you manufacture directly or use contract manufacturers. Discuss supplier agreements, testing, batch records, and the process for investigating complaints.

Distribution and recall planning

Outline online, marketplace, retail, and international sales. Explain how products can be traced through the supply chain and who would coordinate a withdrawal or recall.

Connect the policies with the way you operate.

Product liability and recall are distinct review topics. Inventory, transit, cyber, and other business exposures should also be considered where relevant. Availability and terms vary with the actual products, operations, and insurer.
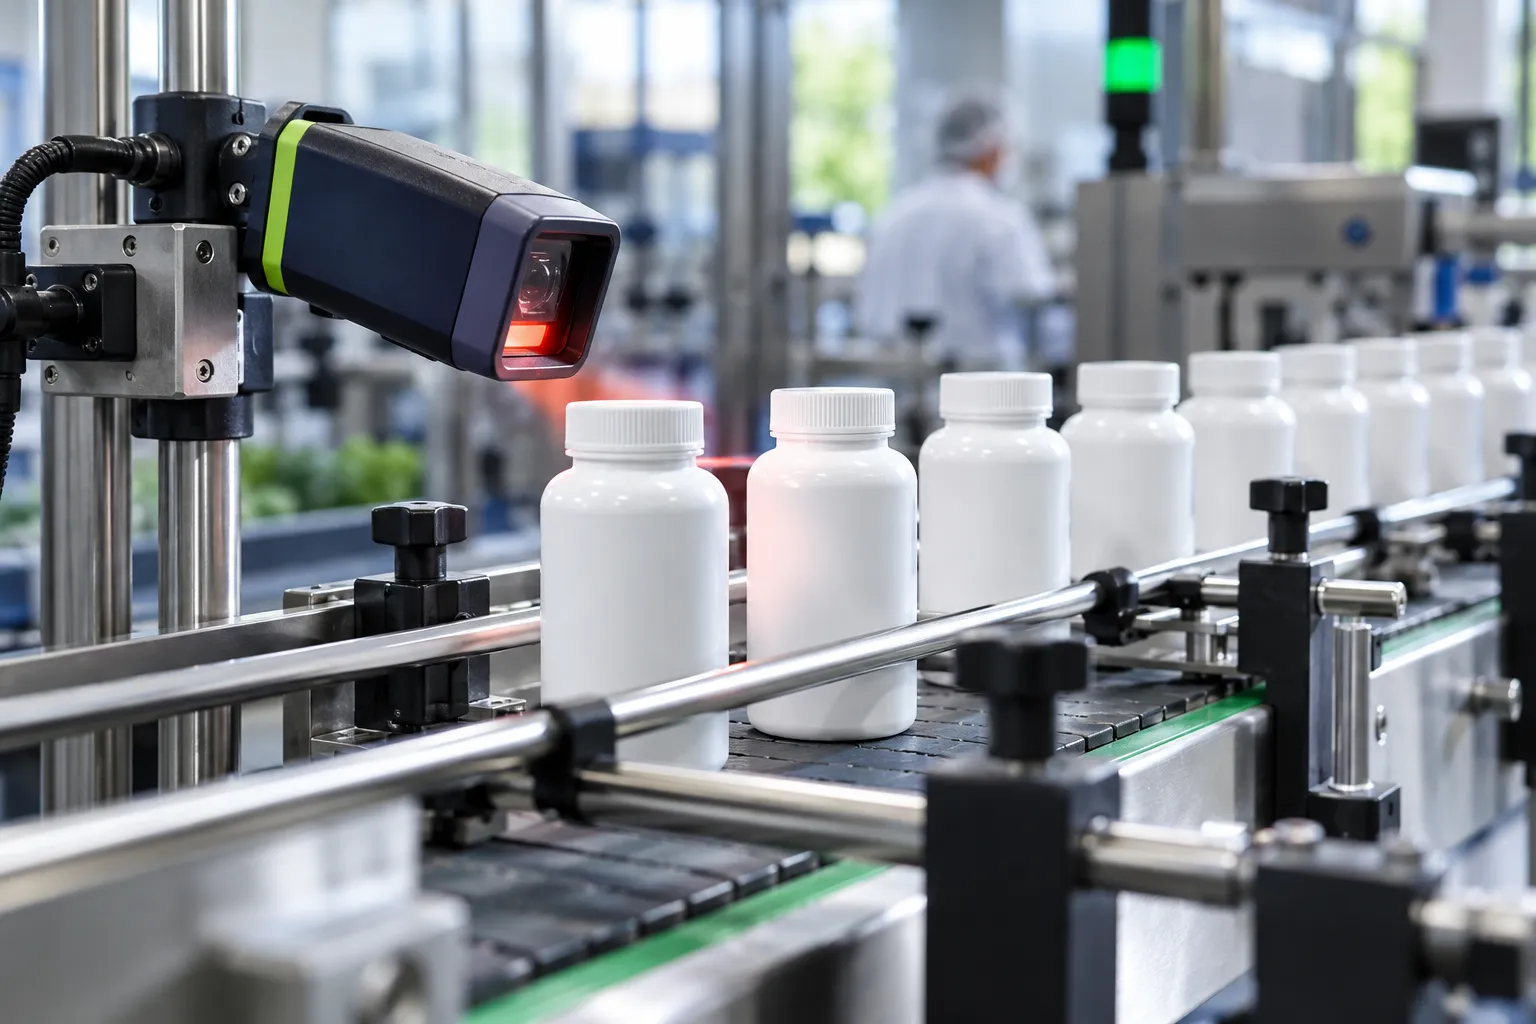
Product bottles passing through an automated quality inspection line.

Make changes in the product range visible

A new formula, manufacturer, intended use, or sales territory can change the questions an insurer asks. Describe skincare, cosmetics, haircare, fragrance, and other categories individually where relevant. Include labeling and marketing claims, complaint handling, batch traceability, and the information available from your manufacturing partners.

How do product liability and recall fit together?

A claim alleging injury from a product and the expense of removing a batch from sale raise different insurance questions. Review the policies separately and compare how the actual products are described. Do not assume a liability policy pays the costs of every withdrawal, refund, or replacement.

What if a contract manufacturer handles production?

Explain the division of responsibility for formulation, ingredient sourcing, testing, labeling, release, and complaints. Bring the manufacturing agreement and relevant insurance documents for review. Outsourcing production does not remove the need to examine your own brand's activities and insurance.

Notebook, calculator, and folder arranged for a business review.

What information helps with a quote?

Start with your website and the date you need coverage. Prepare product categories, revenue, manufacturing locations, sales territories, current policies, and loss history for the next discussion. Flag planned launches and any treatment or professional-service activity separately so they are not overlooked in a product-focused review.

Explore coverage for your business

Review the broader business program

Include premises and operations, employee exposures, and specialist intellectual property questions in the conversation when relevant to your business.

New formula. New manufacturer. Time for a review?

Start with your product range, manufacturing partners, and the change you are planning. Cory will follow up to discuss the business and the information needed for the next step.

Request an insurance review with Cory or call 845-721-0744.

Preparing for the conversation? Download the business insurance review checklist (PDF). No signup required.

Practical reading before your next decision

Explore all business insurance resources

Submitting an inquiry does not bind, amend, or cancel coverage. Coverage availability and terms depend on underwriting and the policy issued.

Is this the same as salon or beautician insurance?

The focus here is product businesses. A company that also operates salons, provides treatments, or offers professional services should describe those activities so they can be considered separately.

Coverage availability, limits, exclusions, and terms depend on underwriting and the policy issued. A quote request does not bind coverage.

‍